
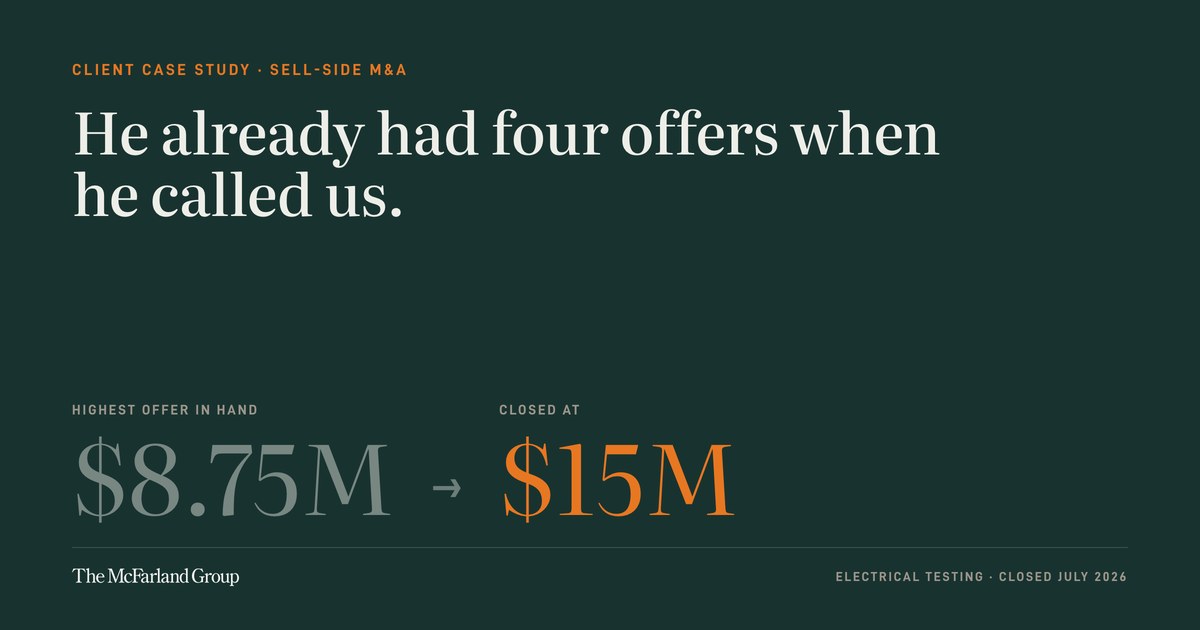
A newly published case study from The McFarland Group details the sale of a founder-owned electrical testing and field services company that closed in July 2026 at $15 million, nearly double the highest of four letters of intent the owner had already received before engaging an advisor. The case study, which the firm has anonymized at the client's request, is intended for owners who find themselves with buyer interest before deciding whether to run a formal process.
The owner had held the business for twenty years and arrived with four signed letters of intent, the highest at $8.75 million. Rather than replacing those buyers, The McFarland Group ran a competitive process around them. All four remained at the table, joined by three additional qualified parties, with every participant working from identical information on the same deadline. The buyer the owner ultimately selected came from his original group, but the terms were not the ones originally on the table. The transaction closed with no escrow and a working capital formula unchanged from the one the firm proposed at the outset, and the owner continues to lead the business.
Because the owner intended to stay on and roll equity, the engagement also weighed fit alongside economics: growth plans, capital appetite, post-closing autonomy, and how each buyer's existing operators described being owned. He elected to roll approximately ten percent of the proceeds. The firm points first to the diligence phase of the case study, where reaching agreement took about six weeks and reaching a closing took three more months. Four diligence teams examined a twenty-year-old, founder-run company, surfacing seven items that were live risks to the transaction. Several were news to the owner himself, including an employment matter from before the sale process, workforce documentation questions, and three separate threads concerning the integrity of the company's S corporation election that carried seven-figure back tax exposure if any had broken. Each was worked through or cleared before closing.
John Bruckner, Managing Partner of The McFarland Group, said the firm could not promise a number, and nobody honestly can, but could promise a competitive field and the backing to get through the part that comes after the handshake. He noted that the months between signature and closing are where deals get retraded, and none of what the firm found was visible on the day the owner was close to signing by himself. The full case study is available at themcfarlandgroup.com/case-study/sell-side-electrical-testing.
The implications extend beyond a single transaction. For founder-owned businesses, the case illustrates that early offers can serve as a floor rather than a ceiling when subjected to a structured, competitive process. It also underscores that the period between signing and closing is where value is most vulnerable, particularly in older companies where employment records, workforce documentation, and tax elections may harbor latent liabilities. The McFarland Group, based in Omaha, Nebraska, and founded by Byron McFarland, has guided over $3 billion in business value through more than 200 ownership transitions over two decades. More information about the firm is available at themcfarlandgroup.com.